

Aspire Account Center

- 967.00 Reviews
- 3.3
- Downloads
- 500,000+
Our take on Aspire Account Center from Appgk
Managing a credit card from a phone sounds simple, but the right app depends on what you actually need to do. I looked at Aspire Account Center as a practical finance tool rather than as a general budgeting app, and that distinction matters. It is built around keeping an Aspire credit card account within reach, not around replacing every money app on your phone.
That focused approach can be useful when I want to check my account without opening a browser or searching through old emails. It can also feel limited if I expect detailed spending analysis, household budgeting, investment tracking, or support for cards from several unrelated providers. My recommendation therefore depends less on whether the app is “good” in the abstract and more on whether your everyday financial routine is centered on an Aspire card.
How I would decide whether it belongs on your phone
The first question is ownership. Aspire Account Center is developed by Atlanticus Services and is intended for managing Aspire credit cards. If that is the card I use regularly, a dedicated account center makes more sense than a generic finance dashboard that may only show imported balances. If I do not have an Aspire card, there is little reason for me to choose this app.
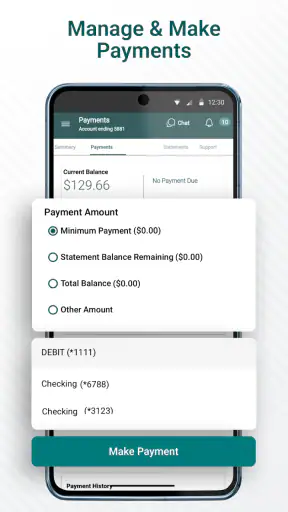
The second question is the kind of control I want. I would use this app for account-focused tasks: checking the current state of the card, reviewing activity, and handling routine card management from one place. I would not approach it as a full personal-finance planner. That difference helps set realistic expectations before installation.
Best Parts of Aspire Account Center
Things to Keep in Mind About Aspire Account Center
It is free to download and has an Everyone content rating, so the basic decision is not about paying for access to the app itself. The more important cost is attention: I still need to read account details carefully, keep login information safe, and verify that an action has completed before assuming the account has changed.
The app has been available since June 25, 2019, and its current version is 4.22.47-6102. It requires Android 6.0 or later. Those details make it accessible to many older Android phones, although compatibility alone does not guarantee that the experience will feel equally smooth on every device.
News and Features Related to Aspire Account Center

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Its average rating is 3.3 from around 2,100 ratings, with about 967 written reviews. I treat that as a reason to keep expectations measured rather than as an automatic rejection. Ratings can reflect login problems, device-specific behavior, account situations, or frustration with financial apps in general. Still, the score tells me to value reliability and recovery options more than visual polish.
The everyday job it handles best
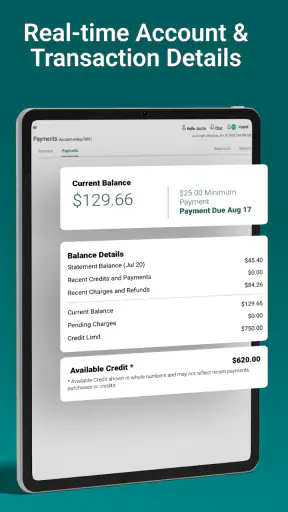
Imagine I am standing in a shop and want to confirm whether a recent purchase has appeared on my card before making another decision. I do not need a budget chart in that moment. I need a direct view of the account, with as little searching as possible. A dedicated card center is well suited to that quick check.
Don't want to read the full review?
The same applies when I am reviewing recent activity at the end of the week. Instead of waiting until I sit at a computer, I can use the phone as the first place to look. That habit is valuable because small unfamiliar transactions are easier to investigate when they are still fresh in my memory.
My practical tip is to treat the app as an account checkpoint, not as a financial autopilot. I would open it after meaningful card activity, compare what I see with receipts, and then close it. That workflow keeps the app useful without encouraging me to mistake a convenient screen for a complete picture of my finances.
Screenshots
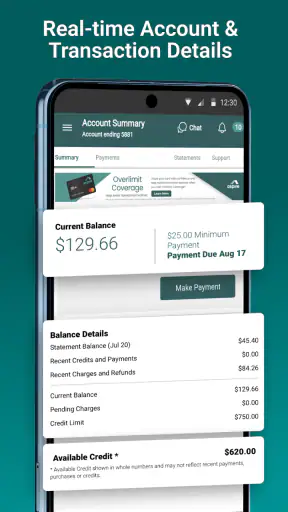
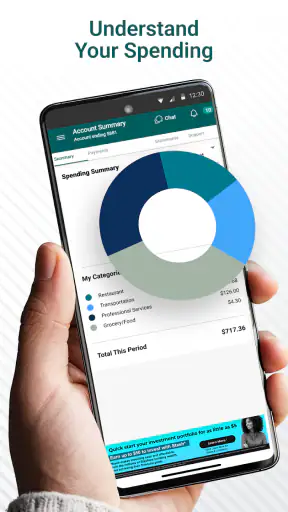
Why the dedicated design can be more useful than a general finance app
Generic money apps usually try to gather information from multiple accounts. That can be helpful for seeing a broad financial picture, but it can also introduce delays, disconnected account data, or a layer of interpretation between me and the card provider. Aspire Account Center has a narrower purpose, which can make it the more direct option for Aspire-specific account management.
I also prefer a provider-focused app when I need to confirm details that a third-party dashboard may summarize too aggressively. A general app might show a balance while leaving me to open another service for the underlying account activity. A dedicated center is more naturally suited to checking the card relationship itself.
The trade-off is equally clear: a narrower app gives me less reason to open it for anything outside that card. If I want to compare grocery spending with utility spending, monitor cash accounts, or plan a monthly budget, I would need another tool. That is not a defect so much as a boundary, but it should shape the installation decision.
Small habits that make the app more useful
I would begin by organizing my routine around events rather than random checks. After a purchase, I can use the account center later to confirm the activity. Before making a larger purchase, I can check the account directly instead of relying on an old notification. At the end of a billing period, I can review activity while the transactions are still easy to recognize.
A second useful habit is separating “I saw the transaction” from “I understand the transaction.” A familiar merchant name may appear differently from the name on a receipt, and a pending item may not look exactly like a completed charge. I would avoid making a dispute or payment decision based only on a quick glance; I would read the available account information carefully and keep supporting receipts.
A third is to use the app as a prompt for broader record keeping. If I am tracking expenses for a household, I would not assume the app alone replaces a spreadsheet or budget. I would record the category and purpose of important purchases elsewhere if I need long-term comparisons. This prevents a common mistake: expecting a card-management tool to become a complete financial archive.
Where it wins, where alternatives fit, and what switching really involves
Situations where Aspire Account Center is the sensible choice
I would choose Aspire Account Center when my main requirement is a direct mobile connection to an Aspire credit card. Its strongest advantage is focus. I do not have to turn a broad budgeting system into a card-management tool, and I do not need to maintain a separate browser routine for every ordinary check.
It is also a reasonable choice for someone who wants a simple starting point. A person who is not interested in linking several financial accounts may prefer one app that stays centered on the card they actually use. The free price removes one barrier to trying it, while the Everyone rating makes it suitable for a broad audience from an age-classification perspective.
For me, the best use case is a cardholder who wants quick access but is comfortable making careful decisions. The app can reduce friction around checking the account, while the user remains responsible for recognizing purchases, watching spending, and following through on any account action.
When a different category is a better match
I would look elsewhere if my main goal were a complete household budget. A budgeting app is usually a better category for combining income, bills, cash accounts, and several cards into one planning view. Aspire Account Center may still be useful alongside that tool, but it would not be my only financial app.
I would also prefer a multi-provider finance app if I regularly use cards from different issuers and want one consolidated place to compare them. The convenience of one dashboard could outweigh the directness of a provider-specific app. The compromise is that imported information may not feel as immediate or as detailed as the account center tied to the original card.
If I mainly use a laptop for financial administration, a browser-based account experience may be enough. In that case, installing a mobile app adds value only if I genuinely need account access while away from the computer. Conversely, if phone access is important, I would favor the dedicated app over saving a browser page and hoping the mobile layout remains convenient.
Someone seeking credit education, debt payoff planning, investment tools, or detailed financial coaching should also compare other categories first. Those needs involve decisions beyond checking a card account. Installing a focused card app will not automatically provide the planning structure required for them.
The friction involved in changing your routine
Switching to a dedicated account center is not only a download decision. I would need to establish a secure sign-in routine, make sure I recognize the correct app from Atlanticus Services, and spend a few minutes learning where the account information appears. A first session should be treated as setup time, not as proof that every future task will be effortless.
I would also avoid uninstalling an existing budgeting app immediately. If that app holds historical spending records or combines several accounts, replacing it with a provider-specific center could create a gap in my financial overview. The safer approach is to let the two tools serve different purposes: use Aspire Account Center for the Aspire card and keep the broader tool for planning.
There is a practical trust issue with any finance app. I would install it only from the official app distribution channel, use a strong account password, and avoid entering credentials on a shared or unsecured device. I would also review the screen after any important action and keep confirmation details when they matter. Convenience is useful, but financial accuracy is more important than saving a few taps.
Another switching cost is habit. If I already check the card through a browser, the app may not transform my finances; it may simply make the same account easier to reach. That can still be worthwhile, especially for frequent checks, but I would not expect the installation alone to improve spending discipline. The benefit comes from building a consistent review routine around it.
What I would want a new user to understand first
The app is free, but the account it helps manage is still a credit account. I would not interpret easy mobile access as permission to spend more casually. Before relying on any displayed figure, I would consider whether a transaction is pending, whether a payment has fully processed, and whether the amount matches my own records.
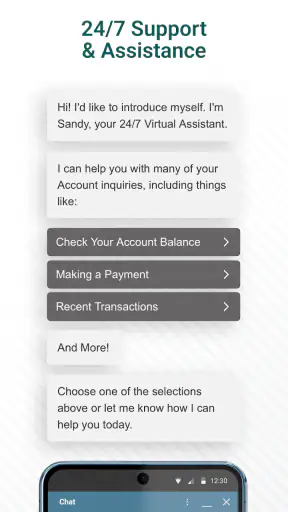
I would also keep expectations realistic about support. A mobile account center can make information easier to reach, but it does not remove the need to follow the provider’s normal procedures when an account issue requires attention. If something looks wrong, I would document the transaction and use the appropriate account-support path rather than repeatedly refreshing the app.
For older Android users, the minimum requirement of Android 6.0 is helpful because it does not force an especially recent operating system. Even so, I would keep the phone updated where possible and leave enough storage for normal app updates. A compatible operating system is only the starting point for a dependable finance workflow.
My recommendation after weighing the trade-offs
I recommend Aspire Account Center to an Aspire cardholder who wants a focused, no-cost mobile way to stay close to that account. It makes the most sense when quick checks and direct account access matter more than a unified view of every financial product. The app’s purpose is clear, and that clarity is its main strength.
I would not recommend making it the center of an entire money-management system. For budgeting across a household, comparing several providers, or planning debt and savings goals, I would choose a broader finance category and use the card center only as a supporting source. That combination is more practical than forcing one narrow app to do every job.
My final decision would therefore be straightforward: install it if you have an Aspire credit card and want a dedicated account companion; skip it if you need a complete financial dashboard or do not use Aspire at all. With that expectation in place, the app can be a useful everyday checkpoint rather than a disappointing substitute for tools it was never designed to replace.
In short, Aspire Account Center is best for direct card access, careful routine checking, and simple account-focused use—not for full financial planning. I would give it a fair trial, keep a second tool for broader budgeting when needed, and judge its value by whether it makes my actual Aspire account routine clearer and easier.
Aspire Account Center FAQ
What is Aspire Account Center used for?
Aspire Account Center is a centralized place for managing information connected with an Aspire account. Depending on the services available in your region, users may be able to review account details, update personal information, manage security settings, access support, and monitor related products or services. It is mainly designed to make account administration easier without having to handle every request separately.
Is Aspire Account Center free to download and use?
The Account Center itself may be available at no additional cost, but the services managed through it can have their own eligibility rules, subscriptions, fees, or transaction charges. Before downloading, users should check the official app-store listing and Aspire’s current terms for their country. Some features may also require an existing Aspire account or an active relationship with a supported service.
Do I need an Aspire account to use the application?
Yes, most of the useful functions are intended for existing Aspire customers or users who have registered for a supported Aspire service. During sign-in, the app may request account credentials, verification codes, or other security information. If you do not already have an eligible account, you may be limited to basic information or directed to the official registration process instead of gaining full access.
How does Aspire Account Center protect my personal information?
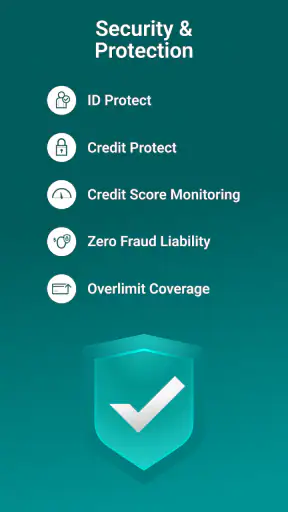
Because the application can involve account and personal details, users should expect authentication and security controls such as password protection, verification codes, session management, and account-recovery procedures. The exact safeguards can vary by platform and region. Use only the official app, keep the application updated, avoid sharing verification codes, and review Aspire’s privacy policy before entering sensitive information.
What should I do if I cannot log in or find a feature I need?
First, confirm that you are using the correct login details, a reliable internet connection, and the latest version of the app. If verification messages are delayed, check your phone number, email inbox, and spam folder. Features can differ according to account type, country, or service eligibility. If the problem continues, use the in-app help options or contact official Aspire support rather than relying on unofficial assistance.











